Gig Worker Insurance: A Design Guide for Platforms
A practical framework for gig worker insurance for delivery platforms india: relevant cover, embedded enrolment, plain-language servicing and usable claims.
Article brief
26 October 2026
9 min read
By Bharatsure Team
Category
Insurance infrastructure
Share
LinkedInQuick answer
Low registration does not equal meaningful protection. Platforms can improve worker insurance outcomes by designing relevant cover around real work risks, placing enrolment within existing journeys and measuring activation, usage and claims support, not just sign-ups.
- Design a protection stack around on-road accidents, hospitalisation-related income loss and disruptions that materially affect a worker’s ability to earn.
- Place enrolment at high-intent moments such as activation, vehicle or document verification, subscription renewal and milestone completion, rather than directing workers to a separate portal.
- Treat policy activation, comprehension, claims initiation, document completion and settlement outcomes as core product metrics alongside enrolment.
- Make claims support operational through contextual in-app entry points, multilingual guidance, human escalation and visible status updates.
For product and operations leaders evaluating gig worker insurance for delivery platforms india, the answer is not another registration link. Build a protection programme around the risks that interrupt work, place it within journeys workers already complete, and run it as a service with measurable activation and claims outcomes. Karnataka’s experience offers a useful warning: a reported 30,256 workers had registered for its scheme against an envisaged around 2.3 lakh as of October 22, 2026. Registration was voluntary, and officials said platform participation had been limited. [Moneycontrol’s report on the Labour Department data](https://www.moneycontrol.com/news/business/startup/karnataka-s-gig-worker-insurance-scheme-sees-tepid-response-only-30-256-registered-14057613.html) is not a verdict on the value of cover. It is a prompt to design distribution and service more deliberately.
Why gig-worker insurance enrolment can remain low despite availability
Availability is only part of adoption. A delivery partner may not enrol if the offer appears outside the app, requires duplicate data entry, uses unfamiliar insurance terms or fails to answer the immediate question: what happens if I cannot work tomorrow?
There can also be a relevance gap. Life or accident cover may be valuable, but a worker managing weekly cash flow may first seek help with accident treatment, a hospital stay or a verified earning disruption. The Code on Social Security, 2020 specifically contemplates schemes for gig and platform workers covering life and disability, accident insurance, health and maternity benefits, old-age protection and other benefits. [Section 114 of the Code](https://www.indiacode.nic.in/bitstream/123456789/16823/1/a2020-36.pdf) offers a useful starting point for a broader protection conversation; it does not prescribe one universal product design.
For platforms, the implication is practical: do not turn gig worker insurance enrolment into a compliance-shaped side quest. Treat it as a worker-experience flow with a clear value exchange, few steps and reliable follow-through.
What insurance cover do delivery and platform workers need?
Start with a risk map, not a catalogue. Segment by work pattern: two-wheeler delivery, four-wheeler ride-hailing, hyperlocal logistics, dark-store picking, EV fleet work and multi-platform work can create different exposure points.
A starting stack for insurance for delivery partners india can include:
- Personal accident cover: protection for specified accidental death, disability and accident-related hospitalisation events, subject to the policy terms.
- Hospital cash: a fixed daily benefit for eligible hospitalisation, which can be easier for a worker to understand than a reimbursement-only promise.
- Health cover: hospitalisation protection for eligible medical events, potentially with an option to extend cover to family members where the programme supports it.
- Income protection: a benefit linked to a defined, verifiable inability to earn, such as hospitalisation; some designs may use objective event triggers. Define triggers, waiting periods and payout rules precisely.
- Life cover: a base financial-protection layer for nominees, where appropriate for the workforce and affordability model.
The Karnataka Platform Based Gig Workers (Social Security and Welfare) Act, 2025 is a reminder that worker protection includes social security, occupational health and safety, registration and platform obligations, not insurance alone. [The official Act text](https://www.indiacode.nic.in/bitstream/123456789/22201/1/72_of_2025_%28e%29.pdf) should be read with applicable rules and legal advice for a platform’s specific operating footprint.
Match each cover to a worker moment and platform risk
The most useful cover connects to a recognisable moment.
| Worker moment | Platform risk to address | Protection design question | |---|---|---| | First activation | New worker begins road-based work | Is base personal accident cover active before the first task? | | Vehicle or document verification | Safety readiness and eligibility | Can the app explain the cover in the same workflow without adding a separate form? | | Weekly earnings view | Income volatility | Does the worker see what is covered, who pays and when the cover renews? | | Hospitalisation or accident report | Immediate loss of earning capacity | Can a worker begin a claim with minimal navigation and receive a case reference instantly? | | Severe-weather or disruption period | Reduced ability to complete tasks | Are event definitions, data sources and payment conditions understood before activation? | | Deactivation or inactivity | Cover continuity | Is the worker told exactly when cover ends, continues or needs renewal? |
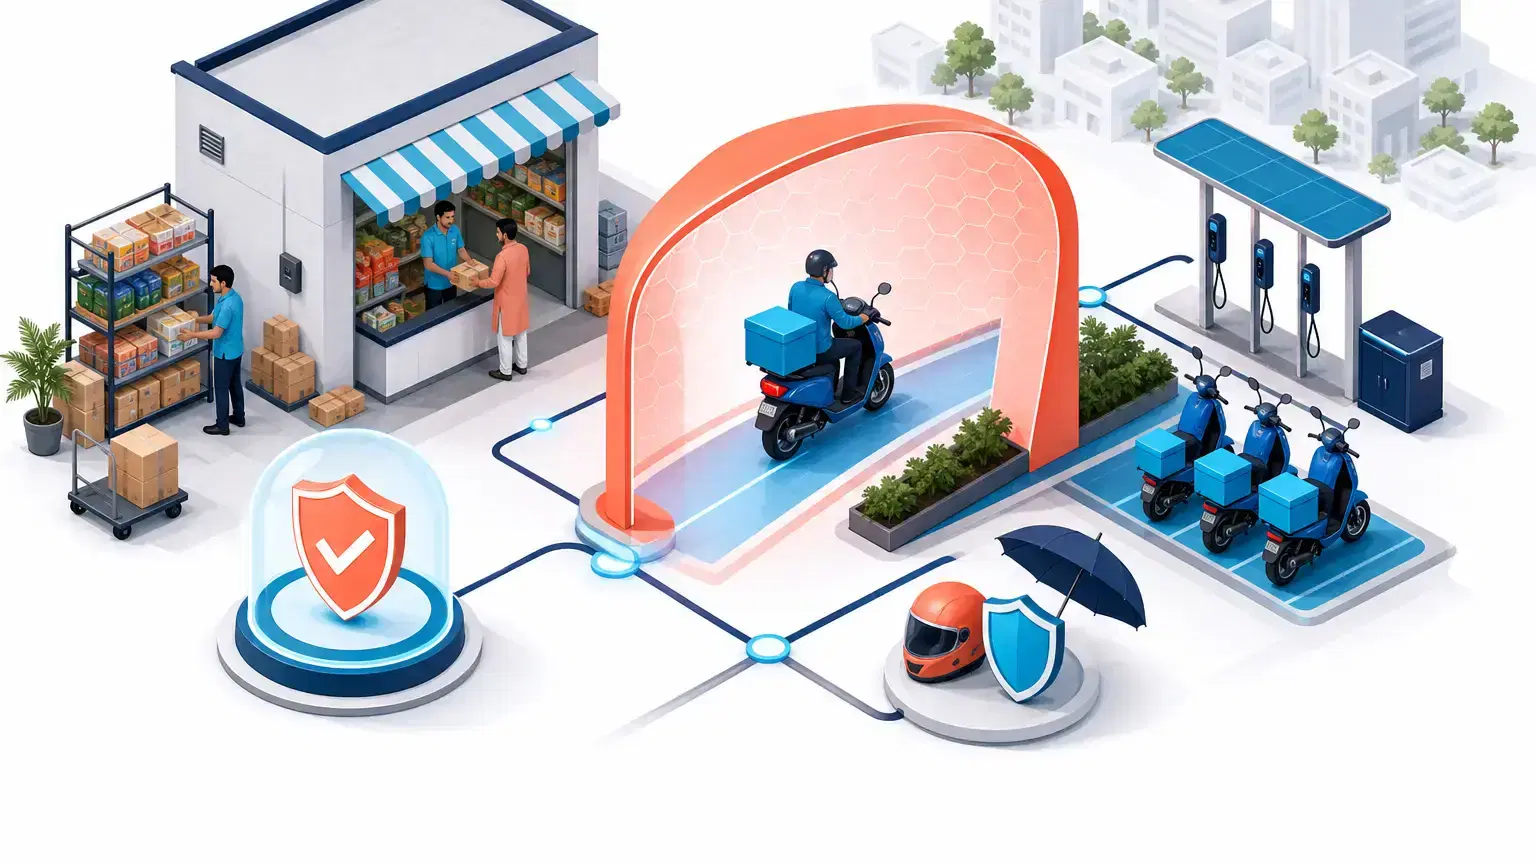
This is where [insurance solutions for gig platforms](/affinity/industries/gig-platforms) become an operating design exercise: select the cover, define the trigger, determine eligibility and map the service route. The aim is not to push every benefit at onboarding. It is to make each benefit discoverable when it becomes relevant.
Where to embed enrolment in the delivery-partner journey for gig worker insurance for delivery platforms india
Embed enrolment where workers already have intent and authenticated data. Good candidates include:
1. Activation completion: Present the foundational cover after KYC and before the first shift, with a two-minute explanation and explicit consent. 2. First earnings or first delivery milestone: Use this point to introduce optional additions or upgrades after the worker has seen value from the platform. 3. Vehicle renewal, battery-swap or subscription screens: For mobility-dependent workers, these are natural moments to restate accident and downtime protection. 4. Weekly payout or incentive view: Show active-cover status, next renewal date and a plain-language claim route, not a promotional banner alone. 5. Safety training modules: Combine completion of a safety step with a short benefits explainer and knowledge check.
An [embedded insurance infrastructure](/affinity) approach can connect eligibility, consent, issuance, servicing and status within the same platform flow. Keep the worker-facing experience short, but retain auditable records of consent, certificate delivery, communications and policy changes.
How to explain policy terms, exclusions and claims in plain language
Insurance trust begins before a claim. Use a layered explanation:
- First screen: “What is covered?”, “What is not covered?”, “When does it start?” and “How do I get help?”
- Second screen: benefit amounts or limits, policy period, waiting periods, nominees and the claims path.
- Full document: policy wording, certificate and insurer-mandated disclosures.
Avoid phrases such as “fully covered” or “instant settlement.” State what the policy actually provides. For example: “A daily hospital cash benefit may be payable for eligible hospitalisation, subject to the policy’s admission criteria, waiting period, exclusions and claim documents.”
Test comprehension, not just clicks. Ask workers to identify whether a sample event is covered, where they would start a claim and how they would nominate a family member. If workers cannot answer those questions, the programme is registered but not meaningfully activated.
Building claims support that workers can actually use
Claims are the product’s moment of truth. Design for urgency, limited familiarity with documentation and the possibility that the worker is injured or unable to earn.
A usable flow should provide:
- an in-app “Report accident / start claim” action from the worker home screen;
- a short initial intake that captures the event date, location, type of help required and a callback preference;
- a checklist that changes by claim type rather than a generic document dump;
- multilingual status messages that explain the next action and expected review stage;
- a human escalation route for bereavement, disability or stalled cases; and
- operational reporting on turnaround at each stage.
A [claims tracking and servicing layer](/claims-infrastructure) can help platform teams keep claim status, servicing tasks and escalations visible instead of leaving workers to chase multiple parties. Still, claims eligibility and payment remain subject to the applicable policy wording, insurer assessment and required documents.
FAQ: Should platforms offer optional or default worker cover?
Should foundational protection be default?
It can be appropriate when the cover addresses a core work risk and the programme has clear consent, eligibility, funding and servicing design. Default inclusion should never mean hidden terms. Workers should know the effective date, cost allocation, scope of cover and how to access support.
When does optional cover work better?
Optional cover is useful for additions that depend on individual preference, such as higher limits, family inclusion or life cover. Place it after the worker understands the base benefit, and do not force a decision during a stressful or time-critical workflow.
Who should pay for the premium?
Platform-paid, worker-paid and shared-cost models can each be workable. Decide based on the risk being addressed, worker affordability, programme objectives and applicable legal and tax advice. Explain the funding model in the same place as the benefit summary.
Metrics that show whether a worker-protection programme is working
Registrations are only the top of the funnel. Create a scorecard with these measures:
- Eligibility-to-offer rate: share of eligible workers who actually see the programme.
- Offer-to-consent rate: whether the message and placement work.
- Consent-to-issued-policy rate: whether hand-offs, data validation and issuance are reliable.
- Certificate-view rate: a practical signal that the worker has received proof of cover.
- Comprehension rate: performance on short, voluntary in-app checks about benefits and claims.
- Claims-start success rate: workers who successfully create a claim case after selecting the claim entry point.
- Document-completion time: where workers get stuck.
- Service-level adherence and resolution time: operational measures for the platform’s service design.
- Claim outcome and reason-code trends: reviewed with the insurer and servicing partners to identify recurring exclusions, data gaps or communication failures.
- Worker sentiment after claim closure: whether the experience improved or weakened trust.
Review results by city, tenure, work type, language and device constraints. Do this carefully: the purpose is to identify friction and improve access, not to disadvantage workers based on claims activity.
The lesson from low-enrolment programmes is straightforward: protection succeeds when it is relevant at the point of work, easy to activate and credible at the point of claim. [Book a demo](/contact) to co-design an embedded protection programme for your platform’s workers, with enrolment, servicing and claims in one flow.
Frequently asked questions
Should platforms offer optional or default worker cover?
Use a risk- and affordability-led approach. A platform may consider default inclusion for a foundational benefit where the programme design, consent flow, pricing and applicable requirements support it. Optional upgrades can then add higher limits or family protection. In either case, make the premium payer, cover period, consent and cancellation process clear before issuance.
Which cover should a delivery platform prioritise first?
Start with the most material and frequent work-related risk in the platform’s operating model. For road-intensive fleets, personal accident cover is often the foundational layer. Add hospital cash or income-protection design where a hospital stay or verified disruption can interrupt earnings. Actual benefits, exclusions and claims eligibility must follow the policy wording.
What should a platform show a worker after enrolment?
Show a simple confirmation screen with the policy or certificate reference, effective dates, covered events, key exclusions, claim-start button, helpline or escalation route, and a link to the full policy wording. Send the same information through the worker’s preferred communication channel.
Sources
- www.moneycontrol.com — moneycontrol.com
- www.indiacode.nic.in — indiacode.nic.in
- www.indiacode.nic.in — indiacode.nic.in