IRDAI Four-Part Motor Insurance Structure: Partner Readiness
The IRDAI four-part motor insurance structure takes effect on 15 December 2026. What insurers and embedded partners should map now.
Article brief
15 November 2026
12 min read
By Bharatsure Team
Category
Insurance infrastructure
Share
LinkedInQuick answer
IRDAI has issued a four-layer motor-policy structure for private cars and two-wheelers. This guide separates confirmed insurer requirements from practical readiness work for EV, mobility, lending and embedded-insurance partners.
- The four-layer structure is set out in IRDAI Circular IRDAI/CIR/MOT/10/2026 and applies to private-car and two-wheeler policies issued on or after 15 December 2026.
- The circular is addressed to all general insurers other than stand-alone health insurers and specialised insurers.
- The policy must show the cover and premium for each section, while the completed customer option form becomes part of the policy and a Customer Information Sheet must be issued at sale.
- For embedded partners, the circular does not prescribe API specifications. The practical work is to map insurer-approved selections, disclosures, document delivery, policy schedules, endorsements and servicing hand-offs.
- Existing policies are not automatically replaced. Section II legal-liability cover may be added during the policy term, subject to an additional premium and an endorsement from the insurer that issued the third-party policy.
The IRDAI four-part motor insurance structure is set out in Circular IRDAI/CIR/MOT/10/2026, dated 2 November 2026. The IRDAI-issued circular is hosted by Ricago in this published copy. It sets out a four-layer format for private-car and two-wheeler motor policies issued on or after 15 December 2026. The directions are addressed to all general insurers other than stand-alone health insurers and specialised insurers. For insurers, EV companies, mobility platforms, lenders and embedded-insurance partners, the immediate task is to translate the insurer’s approved product configuration into a journey that records selections clearly, delivers the required documents and keeps policy, endorsement and servicing data aligned with the issued schedule.
What the reported IRDAI four-part motor insurance structure changes and what remains unconfirmed
The IRDAI four-part motor insurance structure separates private-vehicle motor cover into four sections: third-party liability; legal liability to occupants or pillion riders, including the insured’s employees; personal accident cover; and own-damage cover for the insured vehicle. Third-party liability is mandatory. Within personal accident cover, cover for the owner-insured is mandatory, while cover for occupants, pillion riders and drivers other than the owner-driver is optional. Legal liability to occupants or pillion riders and own-damage cover are optional. These provisions appear in the IRDAI-issued motor-insurance circular hosted by Ricago.
The scope is directed to all general insurers other than stand-alone health insurers and specialised insurers. The circular requires general insurers carrying on motor-insurance business within that scope to provide the structure for private vehicles, including new cars and new two-wheelers. It does not direct stand-alone health insurers or specialised insurers under the addressee stated at the beginning of the circular. The addressee and vehicle scope are stated in the published copy of the IRDAI circular.
The confirmed requirements are material to partner journeys. Insurers must use the prescribed structure and uniform wordings, obtain a completed option form, issue a Customer Information Sheet at the point of sale, and show the cover selected and premium charged for each section in the policy schedule. The completed option form must form part of the policy. These requirements appear in the IRDAI circular dated 2 November 2026.
Several implementation details should not be assumed. The circular does not prescribe a common platform API, a universal checkout layout, one premium for optional sections or a standard workflow for every add-on. It allows insurers to innovate on own-damage cover and determine its pricing, subject to the circular’s limits on restricting the basic cover. Treat insurer product files, approved wordings and integration specifications as the operating source of truth for each offer. These limits and flexibilities are set out in the published copy of IRDAI Circular IRDAI/CIR/MOT/10/2026.
Does the four-part motor insurance structure start on 15 December 2026?
Yes. The circular dated 2 November 2026 says that the four-layer structure, standard wordings and option form come into force on 15 December 2026, and that policies issued from that date must conform to it. It addresses private vehicles, including private cars and two-wheelers, and directs all general insurers carrying on motor-insurance business other than stand-alone health insurers and specialised insurers to provide the cover under this structure. The effective-date requirement appears in the IRDAI-issued circular hosted by Ricago.
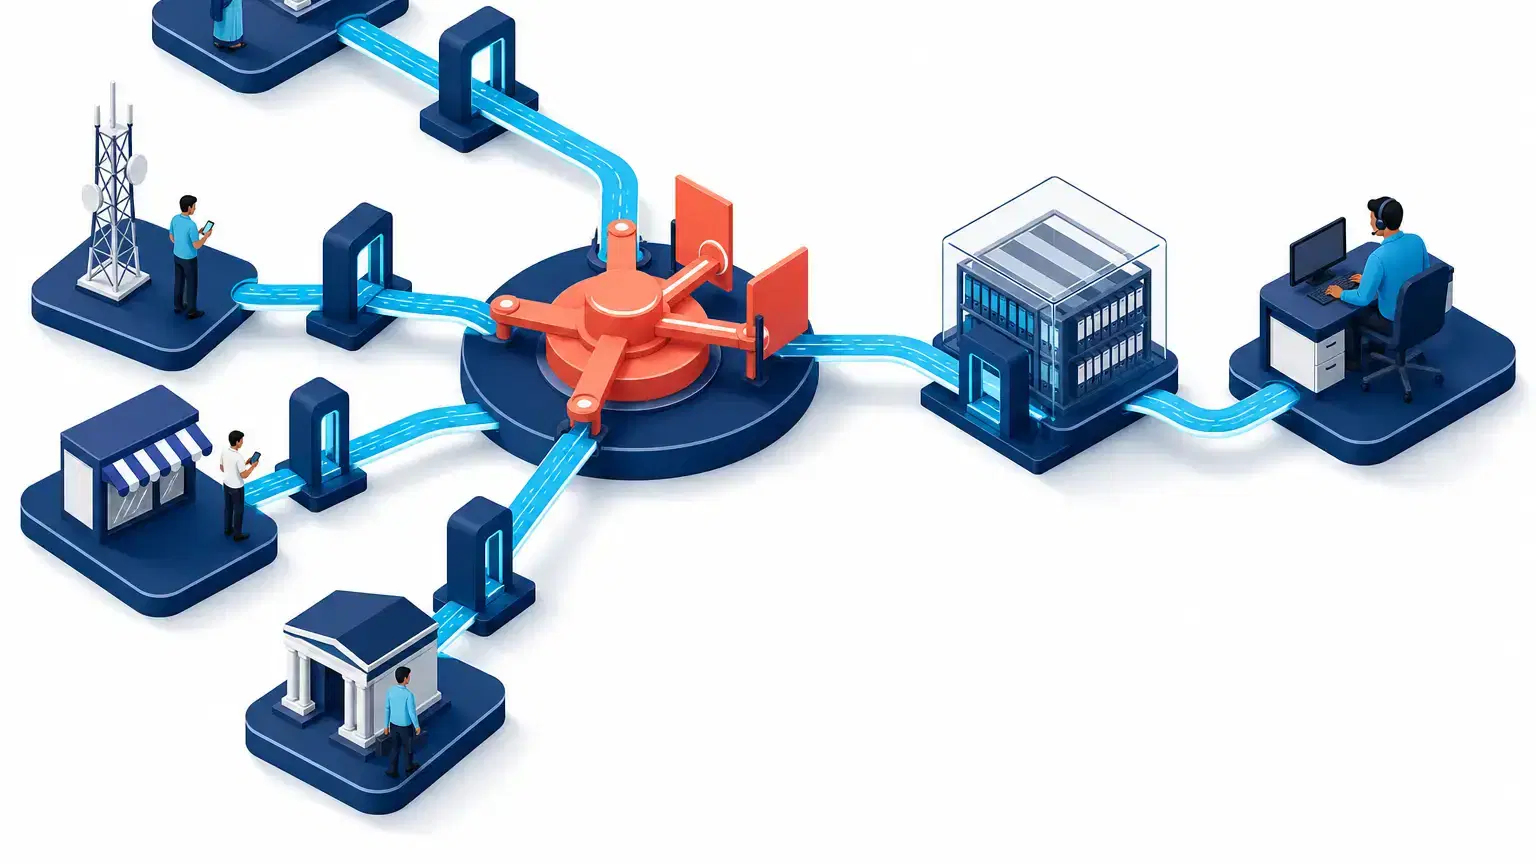
For a lender or mobility platform, this does not mean every motor-related customer journey changes in the same way on the same day. A private EV scooter purchased through an OEM-led checkout, a financed private car and a renewal offer may use different insurer integrations and document flows. The key control is to identify which offers result in a policy issued on or after 15 December, then validate their insurer-approved configuration before that issue date.
The circular also directs insurers to complete integration of the four-layer structure with Bima Sugam so the policies are available there from the same date. Bima Sugam is established under the IRDAI Bima Sugam Regulations, 2024 as a digital insurance marketplace intended to support functions including insurance purchase, policy servicing, claims settlement and grievance redressal. The integration direction appears in the IRDAI motor-insurance circular.
How the structure could affect motor-cover journeys for EV and mobility platforms
The customer-facing change is likely to be a more explicit component-selection journey. Rather than presenting an undifferentiated motor bundle, a platform should be able to show the selected sections, the sections that are optional, the premium associated with each selected section and the documents issued after purchase. That approach follows the schedule-level disclosure and option-form requirements in the IRDAI circular.
For an EV OEM or dealer platform, this matters at vehicle purchase. The vehicle, registered-owner, financing and delivery data may be available before the insurance selection step, but the customer’s choices still need to be presented and captured in the insurer-approved form. For a lender, the same discipline applies at loan disbursal: do not treat a loan-linked motor offer as a background field that can be silently preselected or altered after the customer has completed the insurer’s selection process.
Mobility businesses should also distinguish a private vehicle policy from covers designed for fleets, commercial vehicles, drivers or gig workers. The circular’s stated scope is private cars and two-wheelers. It should not be used as a reason to relabel a commercial or worker-protection offer without insurer and compliance review. Teams designing insurance journeys for mobility and platform businesses should map each use case to its actual vehicle class, insured person, product wording and insurer configuration. The scope is stated in IRDAI Circular IRDAI/CIR/MOT/10/2026.
Product and policy-data changes partners should map before the effective date
Build a product map at section level. For every applicable insurer product, capture the product identifier, vehicle category, Section I to Section IV eligibility, mandatory or optional status, selected limits or variants where applicable, premium by section, taxes, wording version and document templates. The circular requires the policy schedule to reflect actual coverage and the premium charged against each section transparently. These requirements appear in the IRDAI motor-insurance circular.
Then map the events that create or change a policy record:
- Quote and selection: Present only insurer-approved options and retain the selected section values that are passed to the insurer.
- Issue: Reconcile the confirmation received from the insurer against the policy number, schedule, selected sections, premium components and issue timestamp.
- Document delivery: Make the policy schedule, completed option form and Customer Information Sheet available in the agreed channel. The circular makes the option form part of the policy and requires the Customer Information Sheet at the point of sale. See the IRDAI circular requirements.
- Reconciliation and exceptions: Route declines, unavailable optional sections, premium changes and document-generation failures to an operational queue before representing that cover as active.
This is a practical data-design exercise, not a published IRDAI API standard. Teams using API infrastructure for embedded insurance should define versioned insurer payloads and a clear source-of-truth hierarchy so that a checkout screen never outruns the issued policy schedule.
Disclosure, consent and servicing checkpoints at checkout, vehicle purchase and loan disbursal
At checkout, the durable record should be the insurer-approved option form, not only a platform analytics event. The circular requires customers to receive the option form at purchase and permits choices to be made by tick, online or offline. It also requires a Customer Information Sheet at the point of sale. These requirements are set out in the IRDAI circular.
Design the flow so a customer can see, before issue, which sections are mandatory, which are optional, what is selected and what each selected section costs. Avoid labels that imply optional coverage is compulsory, or that a non-selected cover has been issued. The final policy schedule is especially important where an OEM, dealer, lender and insurer each hold part of the transaction record.
At vehicle delivery or loan disbursal, teams should test document availability, customer communication and support hand-offs. A partner may help a customer find policy documents or raise a servicing request, but it should not make coverage promises beyond the issued policy and insurer-approved material. Motor cover, exclusions, endorsements and claim decisions remain subject to the policy terms.
Claims and endorsement workflows to test across each motor-insurance component
The circular does not create a separate claims procedure for each of the four sections. It does, however, make section-level policy selection and disclosure more visible. That makes correct routing and policy interpretation more important when a customer asks whether a particular loss, liability or injury is covered. The structure and disclosure requirements are described in the IRDAI motor-insurance circular.
Test whether the customer-support and claims-intake teams can retrieve the issued schedule, identify the selected section and direct the request to the insurer or claims administrator with the right policy reference. The same test should cover a mismatch between the platform’s displayed selection and the insurer-issued documents. Use claims infrastructure and servicing workflows to define ownership for policy lookup, document retrieval, status updates, insurer escalation and customer communication.
Endorsements need a separate control. The circular permits an existing policyholder to add Section II legal-liability cover during the policy term on payment of additional premium. The risk starts from the date and time shown in the endorsement, and the option is available only from the insurer that issued the third-party policy. Existing third-party insurance need not be cancelled for this purpose. These conditions are stated in IRDAI Circular IRDAI/CIR/MOT/10/2026.
Do not extend that specific rule to every optional section or every add-on without insurer confirmation. Build an endorsement matrix that states what may be added, removed or altered, who initiates the request, when coverage begins and which revised documents must be delivered.
What should a lender or mobility platform do before 15 December?
- Create an offer inventory. Identify private-car and private-two-wheeler motor products that can issue from 15 December 2026, including purchase, finance, renewal and post-sale journeys. The date and vehicle scope are set out in the IRDAI circular.
- Obtain insurer-approved mappings. Confirm section configuration, premiums, wordings, option-form fields, Customer Information Sheet templates, schedule layout, error handling and document-delivery responsibilities.
- Run end-to-end tests. Test every selection combination that the insurer permits, including quote changes, payment failure, issuance failure, duplicate attempts, document retrieval, cancellation where applicable and Section II endorsement requests.
- Train customer-facing teams. Give sales, dealer, loan-operations and support teams plain-language scripts that distinguish selected coverage from optional coverage and refer policy-specific questions to the right insurer workflow.
- Set a release gate. Before changing production customer journeys, validate the final applicable IRDAI notification or circular, the insurer’s policy terms and the compliance requirements applying to the partner’s distribution model.
The date is close, but a rushed interface is not a compliance plan. The right outcome is a journey that accurately reflects the insurer’s issued policy and gives operations teams a usable record when servicing or claims questions arise.
FAQ: Will existing motor policies, add-on covers and embedded offers need changes?
Will existing motor policies change automatically on 15 December 2026? The circular does not state that existing policies will be automatically replaced. It specifically permits Section II legal-liability cover to be added during the currency of an existing policy for an additional premium. The risk begins only from the date and time stated in the endorsement, and the request must go to the insurer that issued the third-party policy. The rule appears in the IRDAI motor-insurance circular.
Do add-on covers need to be rebuilt? Not automatically. The circular allows insurers within its addressee scope, all general insurers other than stand-alone health insurers and specialised insurers, to innovate on own-damage coverage and pricing, and to add or delete general exclusions and conditions based on the coverage chosen, provided the basic four-layer cover is not restricted. Review every add-on against the insurer’s final product configuration, wording and disclosure design rather than assuming one treatment across insurers. See the IRDAI circular.
Will embedded offers require new APIs? The circular sets product-structure, document, schedule and Bima Sugam obligations for insurers within its stated scope. It does not publish a standard API specification for platforms. Partners should map their integrations to the insurer’s final fields, events and documents, then test the full issue-to-servicing journey. The insurer obligations are set out in IRDAI Circular IRDAI/CIR/MOT/10/2026.
Are lenders and platforms directly covered by every direction in the circular? The circular is addressed to all general insurers other than stand-alone health insurers and specialised insurers carrying on motor-insurance business. A lender, OEM, dealer, broker or platform should still align its journey with the insurer’s implementation and its own applicable distribution obligations, contracts and customer communications. The addressee and scope appear in the IRDAI circular.
Mobility, EV and lending partners can Book a demo with BharatSure to map the reported structure against their product catalogue, API events, disclosures, endorsements and claims workflows. Final implementation depends on the applicable IRDAI notification, policy terms and partner compliance requirements.
Frequently asked questions
Will existing motor policies change automatically on 15 December 2026?
No automatic replacement is stated in IRDAI Circular IRDAI/CIR/MOT/10/2026. The circular permits Section II legal-liability cover to be added to an existing policy during its term on payment of additional premium, with risk starting at the time stated in the endorsement. The option is available only from the insurer that issued the third-party policy.
Do add-on covers need to be rebuilt under the four-layer structure?
The circular does not give a blanket instruction to replace every add-on. It permits insurers to innovate on own-damage coverage and pricing, and to set exclusions and conditions consistent with the basic four-layer cover. Partners should therefore obtain insurer-approved product, wording, pricing and disclosure mappings for each existing add-on.
Do embedded motor-insurance offers need new APIs?
The circular requires insurers to use the four-layer structure, issue the option form and Customer Information Sheet, show section-level cover and premium in the schedule, and integrate the structure with Bima Sugam. It does not publish a technical API standard for platforms. API changes should be based on the insurer’s final implementation specification and the partner’s distribution model.
Sources
- IRDAI Circular IRDAI/CIR/MOT/10/2026 — ricago.com
- IRDAI Bima Sugam Regulations, 2024 — egazette.gov.in