Rooftop Solar Insurance in India: A Partner Readiness Guide
Rooftop solar insurance in India: a practical guide for OEMs, installers, lenders and marketplaces designing relevant asset-protection journeys.
Article brief
11 November 2026
13 min read
By Bharatsure Team
Category
Insurance infrastructure
Share
LinkedInQuick answer
A B2B readiness framework for solar partners assessing where insurance may fit across rooftop-solar installation, finance, operation and servicing journeys.
- Treat insurance as a targeted response to a defined asset or customer-risk moment, not as a generic add-on to every solar sale.
- The reported Phase 2 discussion signals policy and market interest, but it does not confirm a new government-backed rooftop-solar insurance product or its terms.
- A launch-ready partner needs reliable asset data, clear hand-offs between warranty and insurance, and a claims workflow that works after installation.
Rooftop solar insurance in India can become a useful commercial layer for OEMs, installers, lenders and marketplaces when it solves a defined risk problem in the solar journey: protecting an asset after commissioning, supporting finance confidence, or making post-sale service easier to navigate. It should not be treated as a vague checkout add-on. The practical question for a partner is which event creates a protection gap, who needs the protection, and whether the available data and servicing model can support a clear policy and claims experience.
A timely reason to assess that question is the reported discussion around the next stage of PM Surya Ghar. On 3 November 2026, ETEnergyWorld reported that the Ministry of New and Renewable Energy was engaging insurers on tailored rooftop-solar products while Phase 2 was being discussed for a possible March 2027 start. That is a market signal, not an announced insurance scheme or a published product specification. The report on the Phase 2 discussion should therefore prompt design work, not assumptions about future cover, pricing or eligibility.
Rooftop solar insurance in India: the partner opportunity
The opportunity is to make asset protection fit the commercial reality of a distributed solar book. An installer may want a clearer post-commissioning service proposition. An OEM may want a more consistent path for incidents outside product warranty. A lender may want a defined process when a financed asset is damaged. A marketplace may want to offer protection at a moment when the customer is already reviewing system specifications, financing and installation dates.
PM Surya Ghar provides useful context, but it is not itself an insurance programme. The current residential-consumer guidelines say the scheme runs until 31 March 2027 and note that the earlier Grid Connected Rooftop Solar Phase II Programme was subsumed into PM Surya Ghar. The same guidelines contain a model agreement that expects five years of comprehensive maintenance and a five-year system warranty from DISCOM commissioning, with component warranty documents supplied to the consumer. MNRE’s PM Surya Ghar guidelines therefore make it especially important to separate manufacturer or installer obligations from insurable events.
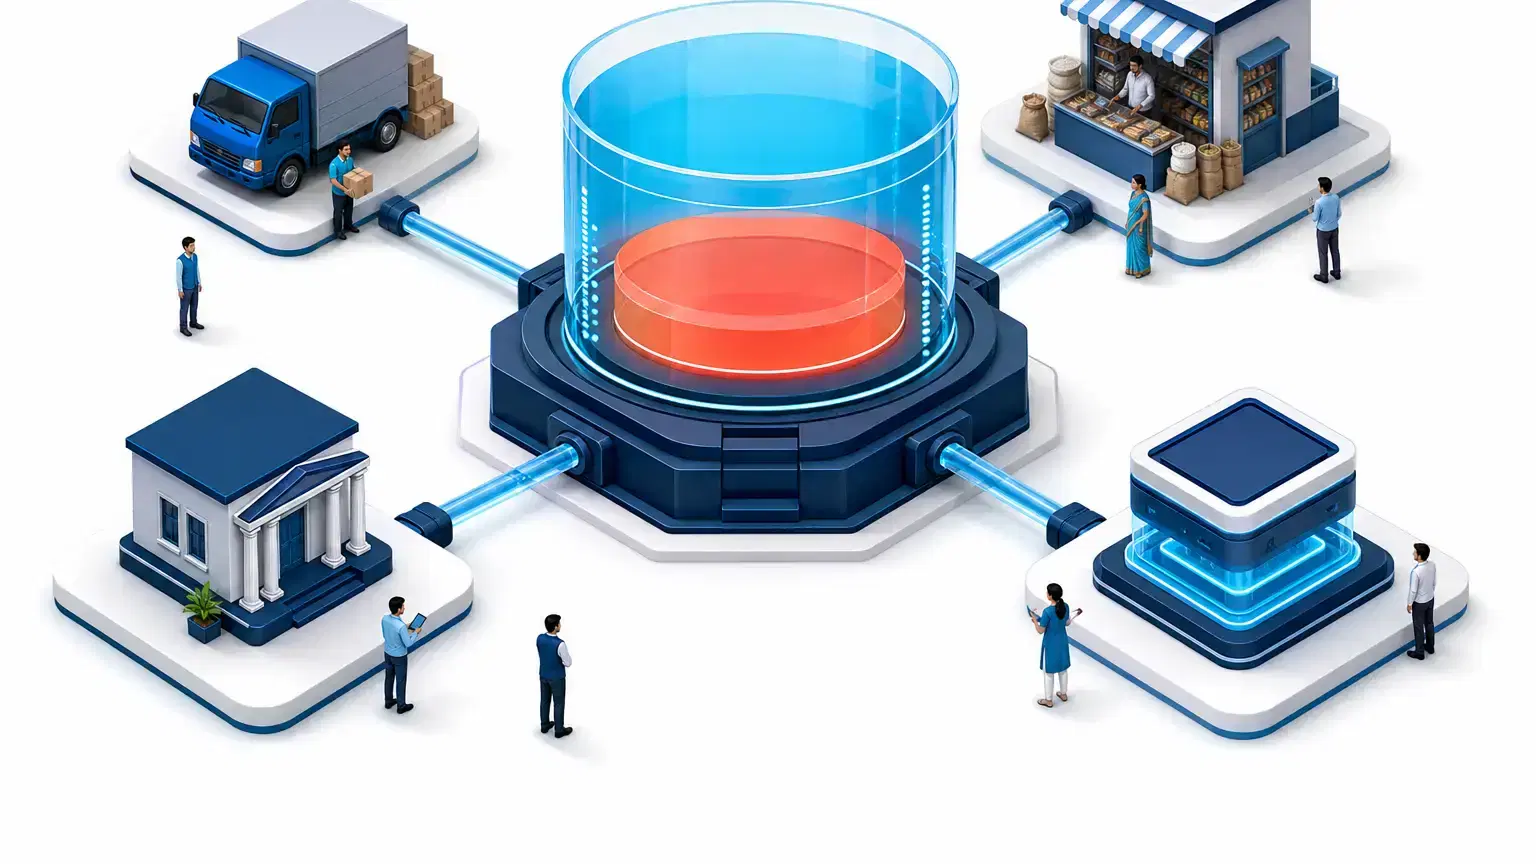
For partners, the first commercial decision is the cohort. A standard residential purchase, a lender-financed installation, a RESCO portfolio and an installer’s annual service base do not present the same risks or economics. Grouping assets with similar system sizes, geographies, component makes, installation controls and documentation standards may create a more workable proposition than trying to arrange protection one household at a time.
This is where embedded insurance for partner journeys can be useful as an operating model. Protection can be evaluated alongside the solar transaction or finance process rather than pushed into a separate, disconnected purchase path. The final product, eligibility and policy wording must be agreed with the insurer, and all cover remains subject to policy terms, conditions, exclusions and deductibles.
What the reported PM Surya Ghar Phase 2 discussion does and does not confirm
The reported discussion confirms only that rooftop-solar insurance is being explored as part of a broader conversation about asset bankability. It does not confirm that Phase 2 has been formally launched, that any customer will automatically receive insurance, or that a standard policy, premium, claims process or subsidy support has been approved. The report described a possible March 2027 start date, so partners should treat that date as reported policy intent rather than a final scheme commitment. The 3 November 2026 report also highlighted the challenge of standalone cover costs for smaller systems and the potential value of aggregation.
The published PM Surya Ghar framework does contain risk-related arrangements that should not be confused with retail or borrower asset insurance. In January 2025, MNRE issued guidelines for RESCO and utility-led aggregation models, including a ₹100 crore Payment Security Mechanism corpus to de-risk investments in RESCO-based residential rooftop-solar models. It is a programme-level payment-security measure, not evidence of a customer solar panel insurance policy. MNRE’s announcement of those operational guidelines distinguishes those alternative models from the national-portal capex route.
Published guidelines also allocate some responsibilities before and after installation. Under the model consumer-vendor agreement, insurance costs for material transfer or storage before commissioning sit with the vendor. The agreement also assigns the vendor responsibilities around site survey, installation, commissioning support, maintenance and warranty assistance. The model agreement in MNRE’s guidelines is a useful baseline for mapping contractual duties before designing any additional protection.
Risk moments across installation, financing, operation and servicing
A credible solar asset insurance India programme begins with a risk map rather than a product name.
Before commissioning: equipment may be in transit, stored temporarily or awaiting installation. The partner should establish custody, invoice ownership, delivery confirmation and the party responsible for loss or damage. Existing vendor obligations and project contracts may already address part of this stage.
During installation and commissioning: site conditions, electrical works, workmanship, approvals and commissioning documents matter. Many issues in this period are better managed through installation controls, quality checks, warranties and contractual remedies than through an insurance promise. MNRE’s model agreement requires vendors to provide technical catalogues, warranty certificates and component serial-number documentation, while supporting the consumer’s portal documentation. These requirements in the scheme guidelines can inform the minimum evidence standard for a partner programme.
At loan disbursal: a rooftop solar financing insurance design should test whether damage or total loss to the asset could impair repayment capacity or collateral value. The lender should define the insured interest, whether the borrower or lender receives claim proceeds, and the process for outstanding-loan reconciliation. These are product-design questions for the insurer, lender and relevant regulated entities, not assumptions to leave for the borrower to interpret later.
In operation: weather events, fire, electrical incidents, theft or physical damage may create an asset-protection need, depending on policy design. Remote inverter or generation data can help triage an incident, but low generation alone should not be positioned as an insured event unless a policy specifically says so. Partners should keep performance, maintenance, warranty and insurance triggers distinct.
During servicing: a customer who sees a damaged module or a system outage needs one clear first point of contact. The partner must decide whether the issue goes to the installer, OEM, insurer, lender or DISCOM, and provide a simple routing rule. A poor hand-off can damage trust even when the underlying policy is appropriate.
Cover concepts solar partners can assess with insurers
There is no single universal answer to solar panel insurance India. A partner can instead evaluate cover concepts against its own asset book and customer journey.
- Physical-damage cover for completed systems. This may be assessed for specified external events affecting panels, inverters, mounting structures or related equipment. The insurer will determine the insured property, sum insured, exclusions, deductibles, repair or replacement approach and evidence requirements.
- Transit and storage cover. This is relevant where the OEM, distributor or installer carries exposure before commissioning. It should align with Incoterms or contractual risk transfer, warehouse controls and delivery records.
- Financing-linked protection. A lender can evaluate an asset cover structure tied to a solar loan, with customer disclosures and claim-proceeds rules designed around the finance agreement. This needs careful coordination with underwriting, lender compliance and collection operations.
- Portfolio protection for RESCO or aggregation models. A commercial structure may be more suitable where one entity owns or manages a large set of comparable systems. Asset registers, maintenance standards and loss history become central to feasibility.
- Installer or contractor liability solutions. These are distinct from cover for the customer’s solar asset. They may be relevant where an installer wants to manage its own contractual or third-party exposure, subject to insurer appetite and policy wording.
A partner should not bundle warranty, maintenance, generation promises and insurance under one label. The customer-facing journey should state, in plain English, what is covered, what is not, which party will respond, how to make a claim and what documents may be needed. That discipline is more valuable than adding multiple covers at once.
For teams that need a broader catalogue alongside bespoke asset-protection discussions, white-label insurance products can support a phased insurance proposition. The solar-specific cover itself should still be validated for suitability, insurer availability and compliance before it appears in a customer journey.
Where to place protection in the solar customer journey
Placement should follow relevance and evidence availability.
At proposal or quote: show protection as an optional design element only after the partner has a credible estimate of system type, value, location and installation model. This is useful for lead qualification, but avoid presenting final cover before underwriting inputs are complete.
At checkout or loan approval: this is often the strongest enrolment moment because asset details, customer identity, invoice value and finance information are already being captured. Consent, policy disclosures and premium payment must be clearly separated from the solar sale or loan documentation.
At commissioning: this is the natural point to validate serial numbers, commissioning date, installed capacity, geotagged photographs, warranty records and customer contact details. It can be the right trigger for post-commissioning protection where the product is designed that way.
At annual servicing: a service visit can prompt customers to update contact details, review cover status and understand the difference between a maintenance request and a claim. It is also a useful point to check whether the asset register is still accurate.
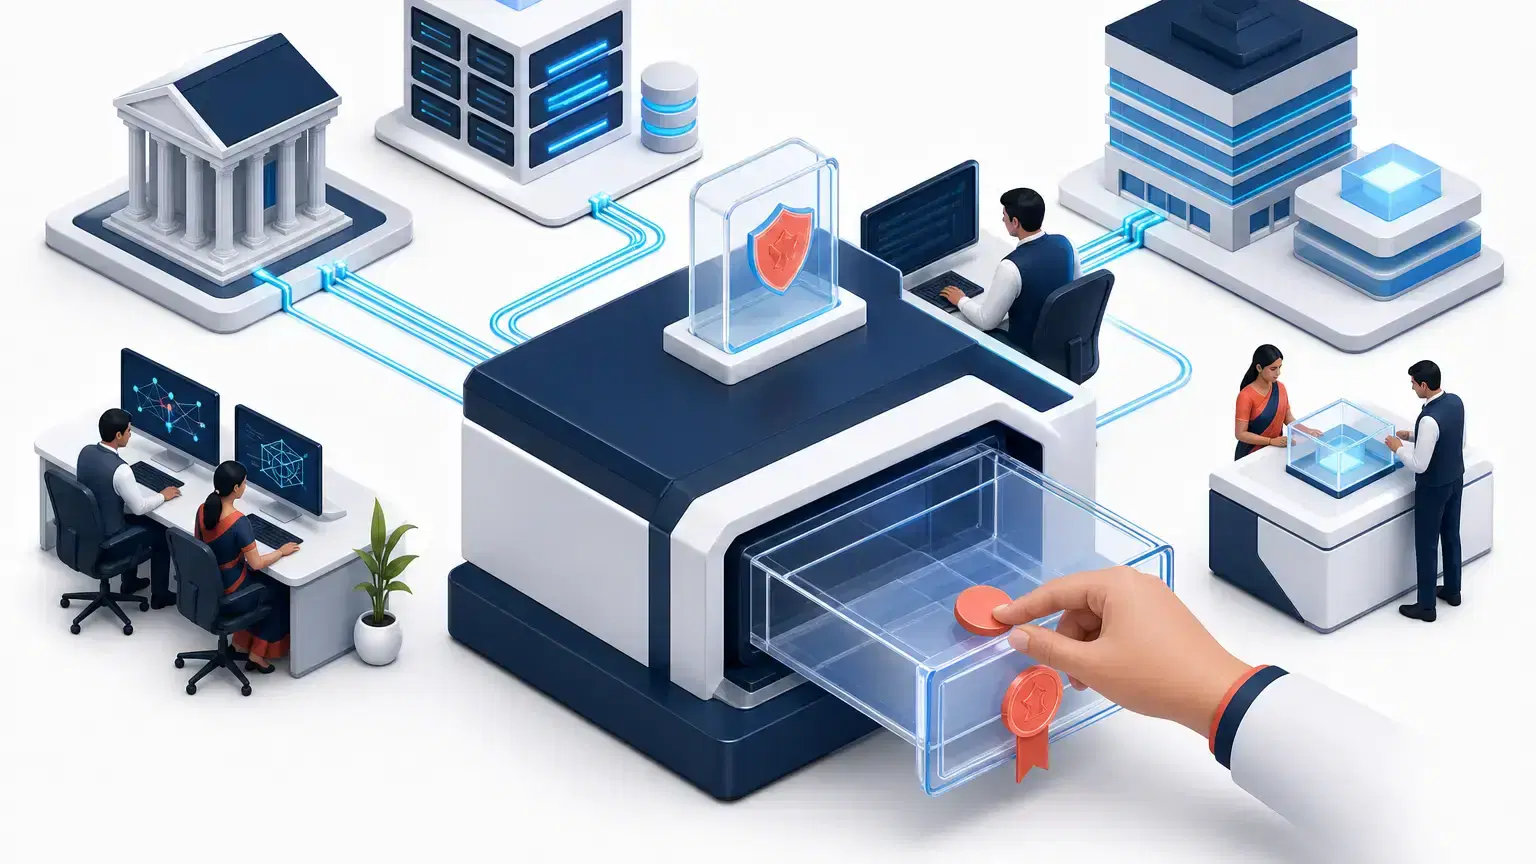
The operating layer should make these triggers repeatable. API-first insurance infrastructure can help partners configure data collection, issue and status checks, communications and policy-document delivery without making solar teams manage fragmented spreadsheets and inboxes. The right architecture is one that supports the insurer’s product rules and the partner’s real servicing process.
Data, servicing and claims workflows partners need before launch
The launch checklist starts with a usable asset record. At minimum, agree the fields needed for customer identity, property address, roof type where relevant, system capacity, panel and inverter make, serial numbers, invoice and financing details, installation date, commissioning evidence, warranty records, geotagged images and service history. Determine the source of each field and who is permitted to correct it.
Next, create a decision tree for incoming incidents. A damaged module after a storm may need insurance triage. A manufacturing defect may need an OEM warranty path. A system that is not commissioned may require installer remediation or DISCOM process support. A customer should not have to decide which internal team owns the issue.
Claims readiness also needs defined evidence standards: date and description of the incident, photographs or video, invoice and asset identifiers, police documentation where a policy requires it, repair estimates, lender details if relevant, and warranty assessment where there may be overlap. The insurer determines admissibility and settlement under the policy. Partners should never suggest that enrolment assures a claim outcome.
A partner can use claims workflows for asset protection to give its team and customers a structured route for claim intimation, document collection, updates and insurer hand-offs. Before launch, set escalation owners, service-level expectations, customer communication templates and reporting for open claims, missing documents and recurring loss causes.
Finally, run a controlled pilot. Start with a defined geography, installation cohort or lender book. Test the data hand-off from quote to commissioning, the policy-document delivery, an installer-to-claims escalation and a realistic customer communication. Use the findings to refine eligibility, disclosures, operational capacity and economics before expanding.
FAQ: Can a solar finance or installation partner embed insurance?
Can a solar finance or installation partner embed insurance?
Yes. A solar partner can assess an embedded programme with an insurer and an appropriately structured distribution and servicing model. The work begins with the business case, asset cohort, data availability and customer moment, then moves to product, disclosures, consent, servicing and claims design. Coverage and eligibility depend on the insurer’s underwriting and the policy terms.
Is warranty the same as rooftop solar insurance?
No. Warranty generally addresses specified defects or performance obligations of the system or component supplier. Insurance can be designed for defined accidental or external loss events, subject to policy wording, exclusions, deductibles and evidence requirements. Under the PM Surya Ghar model agreement, the system carries a five-year warranty from DISCOM commissioning and the vendor is expected to assist consumers with manufacturer warranty claims. MNRE’s model agreement shows why partners need clear routing between the two.
What data is needed to launch solar asset protection?
Partners need a reliable customer and asset record, commissioning and invoice evidence, component identifiers, installation address, warranty information and, where relevant, finance details. They also need pre-agreed ownership of corrections, document collection and claims escalation. This information supports underwriting and service design, but it does not replace the insurer’s policy requirements.
Rooftop solar is a long-lived asset journey, not just a one-time transaction. Partners that define the right risk moment, keep warranty and insurance roles separate, and build an incident-ready servicing path can assess a more useful protection proposition for customers and capital providers. Book a solar-insurance design discussion to explore a co-designed asset-protection journey for a solar purchase, loan disbursal or installer onboarding flow.
Frequently asked questions
Can a solar finance or installation partner embed insurance?
Yes, a solar partner can assess an embedded-insurance programme with an insurer and an appropriately structured distribution and servicing model. The partner should decide the customer moment, eligible asset cohort, cover scope, disclosures, consent, premium collection approach and claims ownership before launch. The insurance policy, insurer underwriting and applicable regulatory requirements determine what can be offered.
Is warranty the same as rooftop solar insurance?
No. Warranty generally addresses specified defects or performance obligations of the system or component supplier. Insurance can be designed for defined accidental or external loss events, subject to the policy wording, exclusions, deductibles and claim evidence. A partner should show customers which route applies before asking them to raise a claim.
What data is needed to launch solar asset protection?
At minimum, partners should be able to identify the insured customer, installation address, system and component serial numbers, commissioning status, invoice value, lender interest where relevant, warranty documents, maintenance history and evidence required after an incident. Data fields should be agreed with the insurer before customer journeys and claims communications are built.
Sources
- Govt Aims for March 2027 Rollout of PM Surya Ghar Phase 2 with Insurance Support for Rooftop Solar, ETEnergyworld — energy.economictimes.indiatimes.com
- # Guidelines for PM-Surya Ghar: Muft Bijli Yojana — mnre.gov.in
- Press Release Page | Press Information Bureau — pib.gov.in