Employee Benefits Platform for Insurance Brokers
Compare an employee benefits platform for insurance brokers by workflow coverage, portals, claims tracking, integrations, implementation support and white-label readiness in India.
Article brief
22 November 2026
14 min read
By Bharatsure Team
Category
Insurance infrastructure
Share
LinkedInQuick answer
A practical guide for Indian insurance brokers and agents evaluating employee benefits software for policy administration, renewals, endorsements, HR and employee journeys, claims tracking and insurer or TPA coordination.
- Choose a platform that covers the complete group-policy lifecycle, not only quotation or enrolment.
- Map separate journeys for the broker, employer, employee, insurer and TPA before selecting technology.
- Prioritise structured renewals, endorsement controls, claims visibility, role-based access and integration support.
- Use sandbox testing to validate real employer scenarios, data migration, insurer hand-offs and service-level reporting.
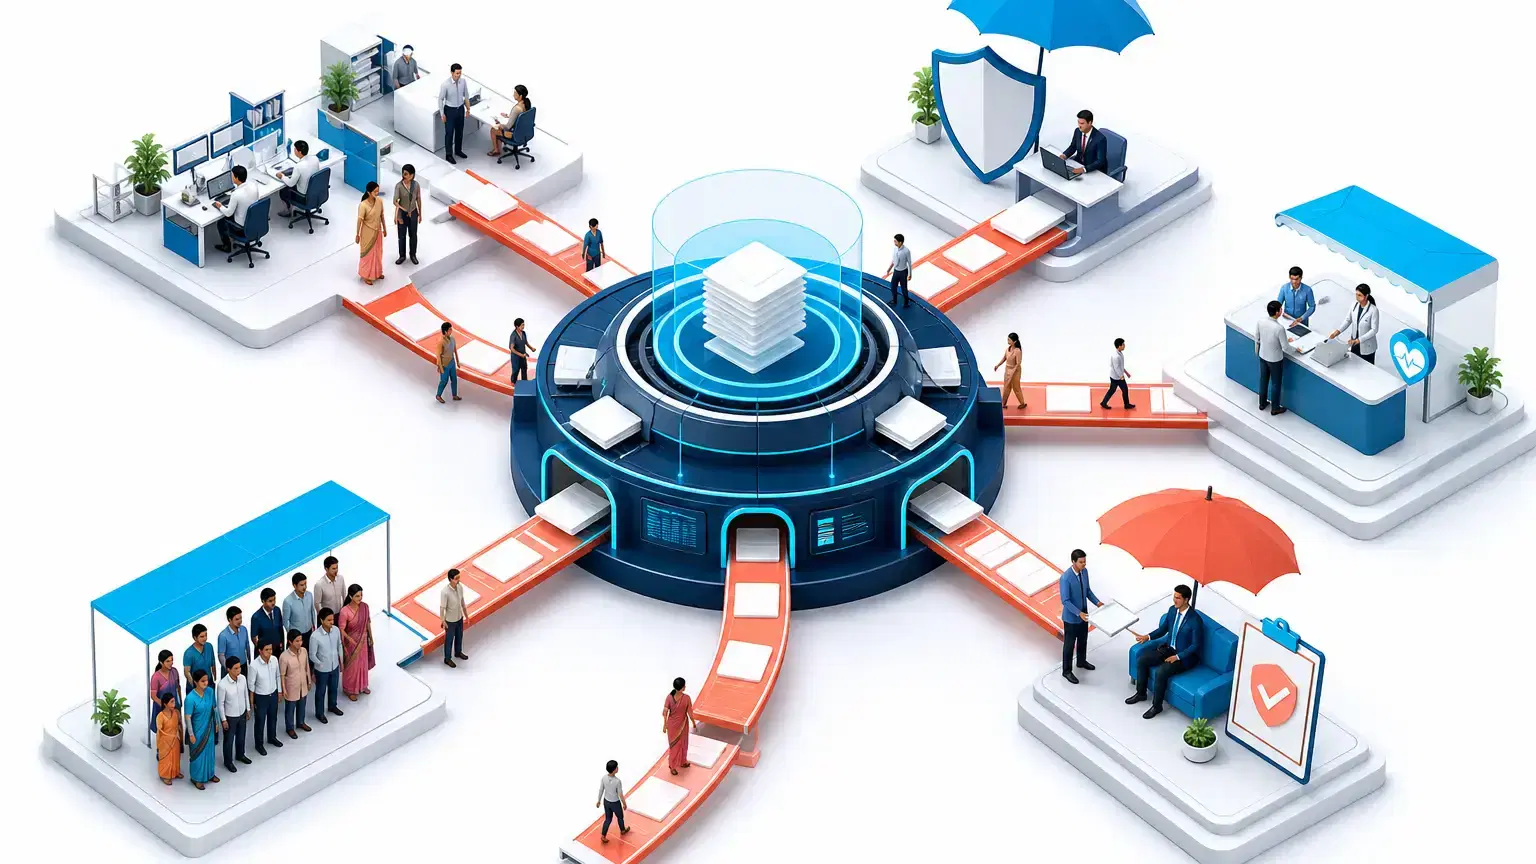
A broker evaluating an employee benefits platform for insurance brokers is usually trying to solve a commercial and operational problem at the same time: win or retain employer accounts while reducing the manual work required to manage policies, employee data, renewals, endorsements and claims. The right platform should give the broker a portfolio-level operating layer, give HR teams clear control over employee benefits and give employees a simple way to access policy information and raise service requests. BharatSure’s employee benefits platform describes this model as a single environment for policy management, claims, endorsements, analytics, member data and quote workflows. (bharatsure.com)
What an employee benefits platform for insurance brokers should manage
Start with the operating model, not the feature list. A group insurance book typically includes several employer accounts, multiple policy years, different insurers and TPAs, varied employee eligibility rules and a steady flow of mid-term changes. A platform should bring these moving parts into a controlled workflow rather than reproduce the same email and spreadsheet process in a new interface.
At a minimum, evaluate whether the system can manage:
- Broker portfolio administration: one broker view across employer accounts, policy periods, products, open tasks, renewals, claims and escalations.
- Employer workspaces: separate access for HR or authorised administrators, with policy summaries, employee master data, pending requests, claims visibility and reports.
- Policy records: insurer, policy number, product, coverage dates, sum insured, employee and dependent data, endorsements, documents and communication history.
- Renewal management: alerts, renewal calendars, utilisation information, quote collection, comparison notes, approvals and migration into the next policy year.
- Endorsement processing: additions, deletions, corrections, dependent changes and other policy updates with validation, approval and audit trails.
- Employee self-service: e-cards, coverage information, network searches, claim initiation, document upload and status updates.
- Claims operations: claim queues, insurer or TPA responses, document gaps, queries, escalations and closure records.
- Reporting: employer-level and broker-level views of policy movement, claims activity, turnaround time, utilisation and unresolved service items.
These capabilities matter because a group insurance broker platform is not just a sales tool. It becomes the working record for the policy year. BharatSure’s broker page describes a multi-client dashboard, white-label deployment, insurer integrations, servicing support and broker-level visibility across separate corporate workspaces. The solutions for brokers and agents are therefore best assessed against the broker’s actual book structure, not only a product demonstration. (bharatsure.com)
How to map broker, employer, employee and insurer workflows
Before selecting employee benefits software for insurance brokers, draw the workflow for each participant. This exposes gaps that a generic product demo can hide.
Broker workflow
The broker needs to create or import an employer account, configure the product and eligibility rules, collect employee data, prepare quotes, coordinate insurer discussions, issue policy documents and monitor service activity. The broker should also be able to see which requests are waiting for employer approval, insurer action, employee information or internal review.
Employer and HR workflow
HR teams need a controlled way to upload or maintain employee data, review additions and deletions, approve requests, download reports and communicate policy information. They should not need broker-level access to unrelated employer accounts. Define user roles early, including HR administrator, finance approver, location administrator and read-only user.
Employee workflow
Employees usually need answers to practical questions: Am I covered? Who is included? Where is my e-card? How do I find a network hospital? What documents are required for a claim? How do I check a pending request? A broker employee benefits portal in India should make these journeys easy on mobile as well as desktop, while directing complex issues to the right service team.
Insurer and TPA workflow
The platform must show what leaves the broker or employer workspace and what comes back from the insurer or TPA. That includes employee data, policy changes, claim documents, queries, approvals, rejections, settlement information and policy records. Do not treat “integration available” as a sufficient answer. Ask which objects, fields, statuses and documents are synchronised, how often updates arrive and what happens when an integration fails.
A useful design exercise is to assign an owner and a required record to every hand-off. For example, an employee addition may require an eligibility date, employee identifier, dependent information, employer approval, premium impact and insurer confirmation. This structure prevents the platform from becoming another place where incomplete requests wait unnoticed. The group-insurance endorsement workflow offers a practical way to separate request types and establish minimum intake fields. (bharatsure.com)
Renewals, endorsements and policy changes without spreadsheet dependency
Renewals and endorsements are where operational discipline becomes visible. A platform should not simply store a final policy document. It should preserve the sequence of decisions and actions that led to the current policy record.
For renewals, look for a timeline that starts well before expiry and includes:
- Policy and employee data review.
- Claims and utilisation analysis.
- Employer objectives and benefit changes.
- Insurer or market quote collection.
- Comparison of terms, coverage and service considerations.
- Employer approval and payment coordination.
- New policy issuance and data migration.
- Employee communication and portal refresh.
For endorsements, create separate queues for additions, deletions, corrections, dependent changes, plan upgrades and other requests. Each queue may have different evidence, approval rules and effective-date logic. A platform should record the request date, requested effective date, approval, premium impact, insurer submission, response and final communication.
This is more than an efficiency preference. Policy documents can require the policyholder to report additions or deletions and may require an endorsement before an additional person is treated as insured. One group health policy wording hosted on the IRDAI domain states that additions may require acceptance, proportionate premium and an endorsement confirming the addition. Brokers should therefore configure their workflows around the applicable policy wording and insurer process rather than assume that an HR upload alone changes cover. The group health insurance policy document is one example of why effective dates, insurer confirmation and member communication need a visible audit trail.
The goal is not to eliminate spreadsheets overnight. Use controlled templates where they are useful, but ensure that the platform validates uploads, records the source file, flags exceptions and converts accepted changes into trackable cases.
Employee and HR portals: the journeys worth digitising
A portal should reduce avoidable service traffic without hiding the broker’s role. Prioritise journeys that happen often and have clear outcomes.
For HR teams, this usually includes:
- Uploading the employee master and dependent data.
- Viewing active covers, limits and policy documents.
- Submitting additions, deletions and corrections.
- Approving requests and reviewing premium impact.
- Tracking open claims and insurer or TPA queries.
- Downloading e-cards, reports and renewal information.
- Viewing the status of requests submitted by different locations.
For employees, the high-value journeys are usually:
- Accessing an e-card and coverage summary.
- Checking dependent details.
- Finding network hospitals or relevant service information.
- Starting a cashless or reimbursement claim journey.
- Uploading documents and responding to queries.
- Checking claim status without repeatedly contacting HR.
- Understanding where to escalate an unresolved issue.
Keep policy language and operational instructions distinct. The portal can explain what a member needs to do, but it should not imply that every claim or request will be approved. Coverage remains subject to the policy terms, conditions, exclusions and insurer or TPA assessment.
For brokers, the key test is whether the portal improves the client relationship. A white-label experience should make the broker more visible as the service owner, while the underlying platform supports the data, workflows, communications and integrations. BharatSure’s broker offering describes branded deployment, separate employer workspaces and background technology and servicing support. (bharatsure.com)
Claims tracking, TPA coordination and service-level visibility
Claims are often the point at which an employer judges the broker’s value. An insurance broker claims tracking platform should show more than a ticket number. It should provide a timeline that can be understood by the broker, HR administrator and employee, with permissions appropriate to each user.
The core claim record should include:
- Claim or reference number.
- Employee and employer account.
- Policy and insurer or TPA.
- Cashless or reimbursement journey.
- Intimation date and current stage.
- Documents received and documents pending.
- Queries raised and responses due.
- Approval, rejection or settlement information where available.
- Current owner and next action.
- Escalation history and communication log.
Ask whether statuses are synchronised automatically or updated manually. Also ask whether the platform captures query letters, document uploads, claim communications, settlement information and analytics across the broker’s book. BharatSure’s claims infrastructure and TPA integrations describes a white-labelled claims dashboard, insurer and TPA connectivity, real-time claim-status information, document and query updates, communication tools and claim analytics. (bharatsure.com)
Service-level visibility should be practical. Define the point at which a case becomes overdue, who receives the escalation, how the employer is informed and how the broker can distinguish insurer delay from missing information. Published service levels are useful only when the platform records timestamps and ownership consistently.
Integration checklist for group health and other employee-benefit products
Integration should be evaluated as an operating responsibility, not only as a technical connection. Use this checklist during product and implementation discussions.
Data and identity
- What is the source of truth for employer, employee and dependent data?
- Can the platform accept HRMS or payroll feeds?
- How are duplicate employees, exits and rehires handled?
- Can the broker map one employee to multiple products or policy records?
- Are role-based permissions available at broker, employer, location and employee levels?
Policy and endorsement data
- Which policy fields are received from each insurer?
- Can the platform support bulk additions, deletions and corrections?
- How are effective dates, premium adjustments and insurer confirmations recorded?
- Can the broker export a complete policy-year record?
- What is the fallback when an insurer does not support an API?
Claims and TPA connectivity
- Which insurers and TPAs are already connected?
- Which claim stages and documents are synchronised?
- Are updates real-time, scheduled or manually entered?
- How are failed updates detected and reconciled?
- Can the broker report claims by employer, insurer, TPA, product, stage and age?
Communications and controls
- Can communications be branded by broker or employer?
- Are email, SMS or in-app notifications configurable?
- Is there a complete activity and audit log?
- Can administrators restrict access to sensitive employee and claim information?
- How are data exports, retention and account closure handled?
Implementation
- Is there sandbox access with realistic test data?
- Who owns data mapping and migration?
- What is the process for validating the opening employee census?
- Which team handles insurer and TPA coordination during go-live?
- What training is provided to broker operations and employer HR users?
- How are product, policy-year and integration changes managed after launch?
A platform provider may offer an existing catalogue, but the broker should still test its own workflows. For example, a broker serving multi-location employers may need different approval paths from a broker focused on smaller SME groups. The strongest implementation plan is the one that makes these differences explicit before configuration begins.
FAQ: Can a broker use a white-label platform across multiple employer accounts?
Can a broker use a white-label platform across multiple employer accounts?
Yes, provided the platform supports separate employer workspaces, role-based access and a broker-level portfolio view. Each employer should have its own policy records, users, documents, communications and reporting boundaries. The broker should retain an overall view of renewals, endorsements, claims and escalations across the book.
Ask for a demonstration of three scenarios: a broker user switching between employer accounts, an HR user restricted to one employer and an employee seeing only their own benefit information. BharatSure states that its broker platform supports multiple corporate clients from one login, with separate client workspaces and broker-level portfolio visibility. The solutions for brokers and agents also describe white-label deployment under the broker’s brand. (bharatsure.com)
Can the platform preserve existing insurer relationships?
That depends on the platform’s integration model and operating agreement. A broker should ask whether existing insurer relationships can be brought into the workflow, which products and TPAs are supported, and how non-integrated partners are handled. Do not accept a general statement about connectivity without testing a real policy, endorsement and claim scenario.
Is a portal enough to replace broker servicing?
No. A portal can standardise intake, make status visible and reduce repetitive queries, but complex cases still need human ownership. Confirm who handles claim follow-up, insurer queries, employer escalations, renewal coordination and exceptions. The best operating model combines self-service with clear service ownership.
How to evaluate implementation, sandbox access and ongoing support
Use a short proof-of-value exercise before committing to a full rollout. Give the provider a representative employer account with anonymised data and ask the team to configure a policy, upload employees, process a dependent correction, submit an addition, open a claim, prepare a renewal view and generate an employer report.
Evaluate five areas:
- Workflow fit: Can your team complete common tasks without workarounds?
- Data quality: Are mandatory fields, duplicate records, dates and exceptions handled clearly?
- User experience: Can HR and employees find policy information and claim actions without broker intervention?
- Operational ownership: Is it clear who handles insurer, TPA and employer follow-up?
- Scale and support: Can the platform manage more employer accounts without multiplying manual work?
Request a written implementation plan covering discovery, configuration, migration, training, sandbox testing, go-live support and post-launch reviews. Ask for named owners rather than a generic support mailbox. Also confirm data export rights, incident handling, integration monitoring, release communication and the process for adding a new insurer or benefit product.
For a broker, the commercial case should be measured in more than reduced administration. Consider whether the platform helps you onboard employer accounts faster, offer a more consistent service experience, improve renewal preparation, create visibility across claims and support additional employee-benefit products. BharatSure positions its employee benefits stack around technology, servicing, products and sales support, while its claims layer can be used alongside employee benefits and other insurance distribution lines. Book a demo to test the model against your own broker workflows. (bharatsure.com)
A practical employee benefits platform for insurance brokers should make the policy year easier to run from first data upload to renewal migration. It should give the broker control, HR teams clarity, employees usable self-service and insurers or TPAs structured hand-offs. For brokers and agents building a scalable employee-benefits practice in India, the next step is to test those journeys with real scenarios rather than compare feature lists alone.
Direct brokers and agents can Book a demo of BharatSure’s white-label employee-benefits platform, with a focus on renewals, endorsements, claims tracking, HR and employee portals, and insurer or TPA connectivity.
Frequently asked questions
Can a broker use a white-label platform across multiple employer accounts?
Yes, if the platform supports broker-level portfolio visibility and separate employer workspaces. Confirm that each employer can have its own users, policies, branding rules, data permissions, communications and reports while the broker retains an overall view.
What should an employee benefits platform show for claims?
It should show claim intimation, document submission, insurer or TPA queries, current status, approval or rejection, settlement updates, communication history and escalation ownership. The exact fields and stages should match the insurers and TPAs in your book.
How should a broker test a platform before implementation?
Ask for sandbox access and test a complete policy year: employer onboarding, employee upload, additions, deletions, dependent corrections, claims, renewal preparation, policy migration and user access removal. Request written answers on integrations, support ownership, data export and service levels.
Sources
- Employee Benefits Platform — bharatsure.com
- Employee Benefits Platform for Insurance Brokers — bharatsure.com
- Claims Infrastructure for Insurance Distributors — bharatsure.com
- Group Health Insurance Endorsements for Brokers: A Workflow Guide — bharatsure.com
- GROUP HEALTH INSURANCE POLICY DOCUMENT — old.irdai.gov.in