IRDAI Distribution Reforms: What an Extended Feedback Window Would Mean for Brokers and Embedded Partners
IRDAI insurance distribution reforms feedback deadline: what brokers and embedded-insurance partners can review after a consultation closes.
Article brief
22 October 2026
8 min read
By Bharatsure Team
Category
Insurance infrastructure
Share
LinkedInQuick answer
The [IRDAI insurance distribution reforms feedback deadline](https://economictimes.indiatimes.com/industry/banking/finance/insure/irdai-to-weigh-650-responses-on-insurance-commissions/articleshow/135435794.cms) closed on October 31, 2026, following an extension. Brokers, insurers and embedded-insurance partners can use the evidence gathered for their submissions to review customer journeys, servicing ownership and operational dependencies while IRDAI considers stakeholder feedback.
- The feedback window for IRDAI’s distribution-reform consultation closed on October 31, 2026.
- The consultation paper proposed changes concerning commissions, expenses of management and distribution architecture. It was not itself a final regulatory framework, as The Economic Times reported on November 2, 2026.
- The IRDAI Expenses of Management, including Commission, of Insurers Regulations, 2024 apply to insurers transacting life, general or health insurance business, commenced on April 1, 2024, and provide for review every three years from notification unless an earlier review, repeal or amendment is needed.
- Brokers and embedded-insurance partners can retain journey maps, servicing records and hand-off evidence to assess operational readiness if the proposals progress.
The IRDAI insurance distribution reforms feedback deadline closed on October 31, 2026. The Economic Times reported on November 2, 2026 that IRDAI would evaluate stakeholder responses after the extended consultation window closed. For brokers, insurers and embedded-insurance partners, the practical task is to preserve the operating evidence behind their submissions and prepare for any later regulatory steps.
What is known about the IRDAI insurance distribution reforms feedback deadline and extension
IRDAI’s consultation paper, Recalibrating Economics of Insurance Distribution, was released on September 23, 2026. Moneycontrol reported that it addressed distribution reforms and costs, including proposals concerning commission limits, insurer expenses of management and the structure of insurance distribution.
The consultation period has now closed. The Economic Times reported that IRDAI had extended the deadline and that the feedback window closed on October 31, 2026.
The consultation was a set of proposals, not a replacement for the notified framework. Regulation 1 of the IRDAI Expenses of Management, including Commission, of Insurers Regulations, 2024 says that the regulations apply to insurers transacting life, general or health insurance business in India and commenced on April 1, 2024.
What brokers and embedded-insurance partners should do after the feedback deadline
The close of the consultation is a useful point to organise the evidence used in a submission and identify operational assumptions that may need review if the proposals move forward. Rather than rely on broad views about distribution economics, teams can connect each concern to a customer journey, a hand-off, a cost centre or a servicing outcome.
Start with a journey map covering the insurer, broker or corporate agent, PoSP, platform, technology provider, call centre, third-party administrator where relevant, and claims-support team. For each participant, record the activity performed, the underlying agreement or procedure, data exchanged, customer communication and the owner responsible when the workflow fails.
Then separate acquisition work from activity that continues after policy issuance. Endorsements, renewals, document retrieval, claims intimation, status updates and grievance escalation all involve operating costs and customer outcomes that may not be visible in a simple sales metric.
Partners that need one operational view across proposals, endorsements, renewals and claims updates can consider insurance infrastructure for brokers.
Which distribution workflows deserve an evidence-led review
The reported consultation proposals addressed commissions, distribution expenses and distribution architecture. That makes it sensible to review the full customer journey, not only the commercial agreement between two entities. Moneycontrol’s report on the consultation paper outlines those themes.
Product and partner selection
Document the intended customer segment, product rationale, insurer approval route and controls over product presentation. Where a platform presents more than one insurer or product, retain the eligibility logic and the rules that govern placement or prominence.
Marketing and customer acquisition
Keep versioned landing pages, scripts, messages, call flows and partner communications. The record should show what the customer saw before proceeding, who approved that material and the dates for which each version was live.
Consent and purchase
Retain records connected to the offer shown to an individual customer: insurer, cover, premium, exclusions, key conditions, channel, language, timestamp and product version. An acceptance record is more useful when it can be matched to the proposition actually presented.
Policy issuance and servicing
Track payment mismatches, failed issuance, document delivery, endorsement requests, renewal exceptions and customer contacts after sale. This helps teams identify whether an issue arose in the insurer workflow, a distributor hand-off or an integration.
Claims support and grievances
Map the point at which a customer first requests help, the owner of the next action and the route by which updates return to the customer. Repeated document requests, unresolved transfers and delayed escalations can reveal service gaps across participating entities.
How to assess customer outcomes beyond sales volume and commission
Sales volume and distributor remuneration do not, on their own, show whether a customer received a clear product presentation or dependable post-sale support. The consultation linked distribution economics with commissions, insurer expenses and distribution architecture. Moneycontrol reported on those proposed themes.
Useful operating measures include:
- issuance success and failure rates;
- cancellations and early exits by product and channel;
- renewal patterns;
- complaint volumes and root causes;
- endorsement and servicing turnaround times;
- claim-intimation completion rates;
- repeated document requests;
- unresolved hand-offs among the platform, distributor and insurer; and
- support contacts per policy.
Segment results by product, distribution channel and customer cohort. A portfolio-wide metric can conceal a recurring issue in one integration, partner flow or assisted-sales journey. The purpose is to connect operating activity with the customer experience and identify where a future distribution change could create a service gap.
What an API-led insurance partner should document on consent, servicing and escalation
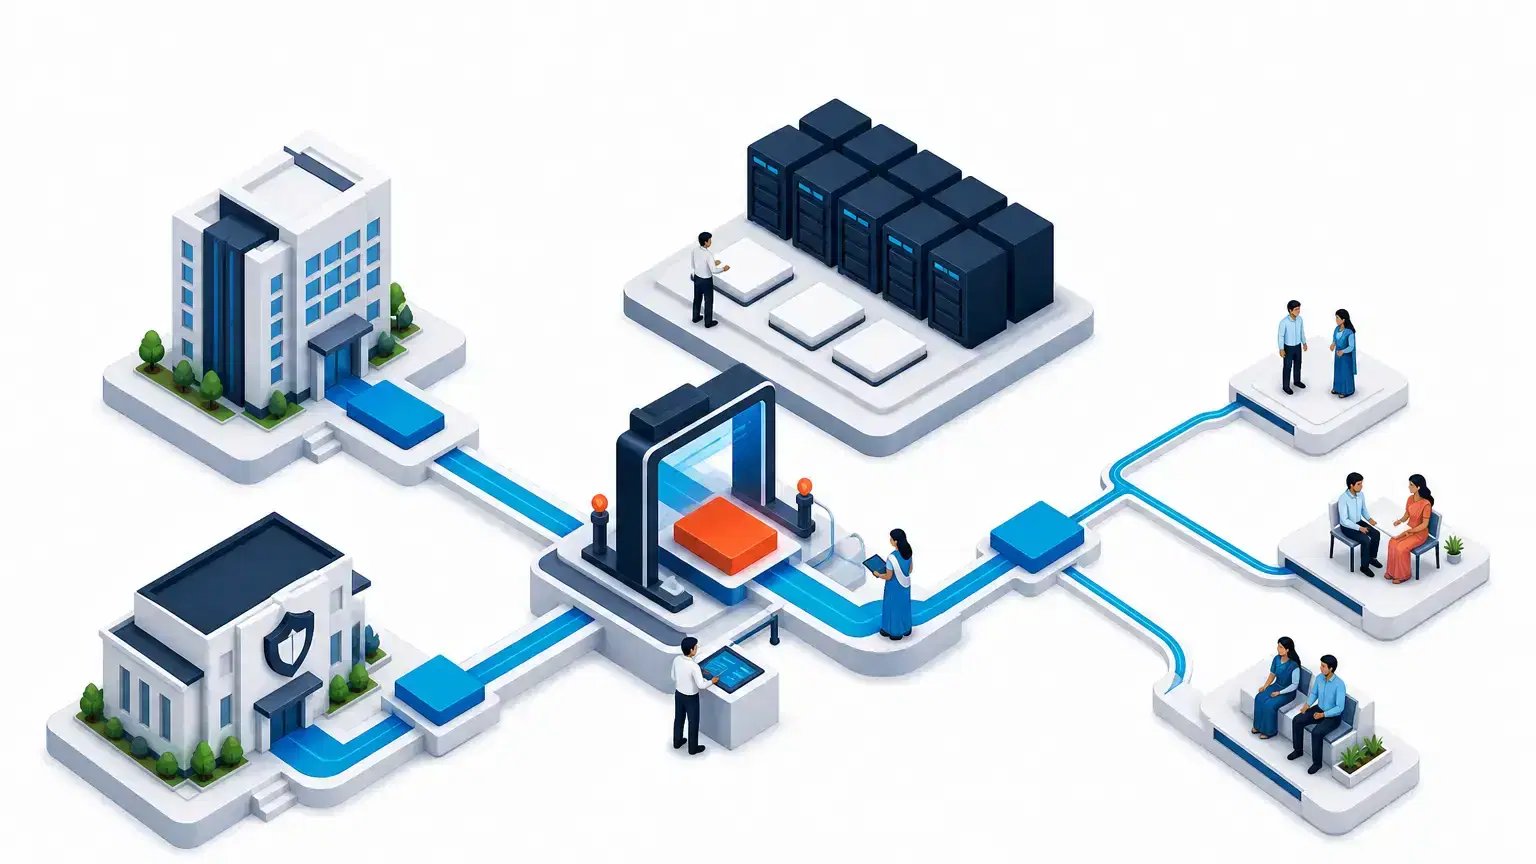
An API-led journey can involve a platform, regulated distributor, insurer and service provider, with records held across several systems. A complete event trail helps teams reconstruct a customer journey and route an exception to the participant responsible for the next action.
Platforms running embedded and affinity insurance programmes should document:
- Product configuration: Product identifier, insurer, wording version, eligibility rules, premium logic and effective dates.
- Customer presentation: Screens, disclosures, messages and communication templates used before purchase.
- Consent evidence: Customer action, timestamp, language, channel, accepted wording and product version.
- Transaction trail: Quote, payment, proposal, issuance and document-delivery events, including retries and failures.
- Role allocation: The participant responsible for solicitation, explanation, issuance, servicing, escalation and customer communication.
- Data movement: Information exchanged among the platform, distributor, insurer and service providers.
- Servicing routes: Processes for endorsements, cancellation, renewal, document retrieval and customer queries.
- Claims support: First notice of loss, document collection, status communication and escalation ownership.
- Exception controls: Treatment of duplicate payments, failed issuance, incorrect customer data and delayed responses.
- Audit trail: Permissions, configuration changes, operational logs and incident records.
This recordkeeping does not alter responsibilities set by regulation or contract. It gives participating teams a clearer way to locate the relevant record, identify the owner of a failed hand-off and improve the customer journey. Partners can explore API-led insurance infrastructure and discuss a compliant distribution workflow.
What has not changed until IRDAI issues a final notification
The consultation and the October 31, 2026 closing date did not themselves amend the notified regulations. Regulation 1 of the IRDAI Expenses of Management, including Commission, of Insurers Regulations, 2024 states that they commenced on April 1, 2024, apply to insurers transacting life, general or health insurance business in India, and are to be reviewed once every three years from the notification date unless an earlier review, repeal or amendment is needed.
On November 2, 2026, The Economic Times reported that IRDAI would evaluate stakeholder responses and that the industry was awaiting draft guidelines followed by a final framework. Teams can use this period to test data quality, identify contract and technology dependencies, and model operational scenarios. Any live change to remuneration, contracts, customer communications or servicing controls should be assessed against the regulatory and contractual position applicable when that change is made.
FAQ: Does a consultation-paper deadline change current insurance distribution rules?
Does the feedback deadline change current rules?
No. A consultation deadline marks the end of the comment period for proposals; it does not itself amend the existing framework. The IRDAI Expenses of Management, including Commission, of Insurers Regulations, 2024 commenced on April 1, 2024.
Was the consultation deadline extended?
Yes. The Economic Times reported on November 2, 2026 that the feedback window was extended and closed on October 31, 2026.
What should partners include in their feedback record?
Retain the specific proposal at issue, the customer or operational impact, the affected distribution workflow, evidence from actual operations and a practical alternative or transition approach. Keep clear assumptions, relevant product or channel distinctions, and the systems or agreements that would need to change.
Should platforms pause embedded-insurance launches?
A consultation and the closing of its feedback window do not, by themselves, determine whether a launch should pause. Before launch, the insurer, distributor and platform should assess the current product journey, customer communications, consent capture, data flows, servicing path and escalation ownership against the arrangements that apply to the programme.
Book a demo to map your distribution, servicing and claims workflows to a white-label insurance programme while regulatory proposals evolve.
Frequently asked questions
Does a consultation-paper deadline change current insurance distribution rules?
No. Closing a consultation period does not itself amend an existing regulation. Regulation 1 of the IRDAI Expenses of Management, including Commission, of Insurers Regulations, 2024 states that the regulations commenced on April 1, 2024.
Was the feedback deadline extended?
Yes. The Economic Times reported on November 2, 2026 that IRDAI had extended the deadline and that the feedback window closed on October 31, 2026.
What should an embedded-insurance partner retain after the consultation?
Retain product configuration, customer disclosures, consent records, payment and issuance events, servicing requests, claims-support hand-offs, escalations and exceptions. This creates a practical record of the owner and system involved at each stage of the journey.
Should brokers change remuneration or partner contracts before final rules are notified?
A consultation response and the closing of its deadline do not, by themselves, amend the applicable framework. Contract or remuneration decisions should be assessed against the regulations, agreements and approvals that apply at the time. The 2024 EoM and commission regulations commenced on April 1, 2024.
Sources
- The Economic Times reported on November 2 that IRDAI would evaluate the responses after the October 31 close — economictimes.indiatimes.com
- Read Moneycontrol’s September 23 report on the consultation paper — moneycontrol.com