PhonePe’s Diwali Cover: A Playbook for Embedded Protection
What PhonePe firecracker insurance signals for platforms designing clear, short-duration festive protection and claims journeys in India.
Article brief
24 October 2026
13 min read
By Bharatsure Team
Category
Insurance infrastructure
Share
LinkedInQuick answer
A reported Diwali firecracker cover on PhonePe shows how payment and consumer platforms can embed event-led protection: start with a relevant moment, explain terms clearly, and build claims support before launch.
- A festive protection programme should centre on a specific customer moment and clearly defined risk, rather than a generic insurance catalogue.
- The purchase screen is only one part of the product. Eligibility, policy documents, exclusions, incident reporting and status updates need equal product attention.
- Platforms should measure informed enrolment and claims-service outcomes alongside adoption, so a short-duration cover builds trust rather than only transactions.
Updated 3 November 2026.
PhonePe’s reported Diwali firecracker cover offers a practical lesson in phonepe firecracker insurance for product and partnership teams. A platform can make short-duration protection relevant when it appears at a high-intent event moment, explains the cover clearly and provides a credible route from purchase to support after an incident. Mint reported on 23 October 2026 that PhonePe made a seasonal firecracker-mishap policy available digitally, underwritten by Aditya Birla Health Insurance. Other platforms need not reproduce that offer. The more useful lesson is how to build the operating model responsibly. Mint’s report
What PhonePe’s reported Diwali cover signals for embedded insurance
The reported programme follows a useful embedded-insurance pattern: connect a defined risk to a time-bound occasion when customers can quickly understand why protection may matter. Rather than asking a customer to browse a broad catalogue, the journey presents one use case, firecracker-related mishaps around Diwali, in an app they already use. Mint reported that the policy included medical cover and was underwritten by Aditya Birla Health Insurance. Mint’s report
For payment apps, marketplaces, mobility businesses and consumer fintechs, the practical starting point is distribution context:
- Identify the event and the exposure. Diwali, travel peaks, monsoon operations or a delivery season can each create a recognisable protection need.
- Match the cover to the exposure. Personal accident, hospital cash, device, travel or another relevant cover should address a defined problem, not simply become another checkout item.
- Keep the offer bounded. State the coverage period, who is insured, benefits, exclusions and the claim route up front.
- Design for service, not only conversion. A customer who needs help after an incident should not need to search old emails or restart the journey.
This is the value of embedded insurance programmes: insurance sits within an existing digital journey while product, insurer relationship, policy servicing and claims hand-offs are designed together.
Can a platform embed short-term festive accident protection?
Yes, provided the platform treats embedded festive insurance India as an insurance programme rather than a campaign widget. A platform must operate in an IRDAI-authorised distribution or servicing role, or work through an arrangement involving an appropriately authorised insurer or intermediary for the relevant insurance activities. The IRDAI policyholder-protection regulations define distribution channels as insurance agents, intermediaries, or persons or entities authorised by IRDAI to participate in the sale and service of insurance policies.
The IRDAI (Insurance Products) Regulations, 2024 took effect on 1 April 2024 and apply to insurers registered to carry on life, general or health insurance business in India. They require insurers to maintain board-approved policies covering product design, underwriting, advertisements and overall product management, and to establish a Product Management Committee. The IRDAI policyholder-protection regulations, also effective from 1 April 2024, apply to insurers and distribution channels other than those engaged solely in reinsurance, unless otherwise specified.
The clear-disclosure duties sit in the policyholder-protection regulations. They require prospectus information to give a true and correct picture of product features, benefits, exclusions, risks and terms in clear and simple terms. They also require policy terms and conditions to be simple and clear, avoid jargon, and avoid coercive, unfair or one-sided clauses. IRDAI’s policyholder-protection regulations
For advertising, the regulations require information to be fair and true, reflect product risks, and avoid misleading or inaccurate presentation. A distribution channel must present advertisements as soliciting insurance products offered by insurers, rather than imply that it offers the product directly. The IRDAI Master Circular on Operations and Allied Matters of Insurers, dated 19 June 2024, reference IRDAI/PPGR/CIR/MISC/97/06/2024, further requires every distribution channel that is an entity to have a compliance officer responsible for advertising-related compliance with the applicable regulations and norms.
For a platform, this means customer-facing copy and servicing flows should be developed with the insurer and should reflect approved product materials, policy wording and operating arrangements. Campaign creative should follow the insurer’s governance process rather than be treated as ordinary promotional copy. The Insurance Products Regulations require advertisements issued by insurers and their distribution channels to be approved through the insurer’s board-approved Advertisement Committee.
The implementation question is simple: which customer moment can responsibly trigger an offer, and what information is needed to issue and service it correctly? A festive campaign hub, merchant app, worker portal or post-payment confirmation can be a distribution surface, but each needs defined data flows, insurer-aligned content and a support model.
A robust launch plan usually has five workstreams:
- Product configuration: Define the insured group, period of insurance, benefit structure, eligibility logic and exclusions with the insurer and relevant distribution partners.
- Journey design: Show a short summary before purchase, then make the full wording, certificate or policy document easy to retrieve afterwards.
- Consent and data controls: Collect and validate the information required for enrolment, issuance and servicing.
- Operations: Prepare support scripts, escalation owners, insurer or TPA touchpoints, document checklists and service-level expectations.
- Measurement: Instrument the journey from offer impression to document delivery, claim intimation and closure.
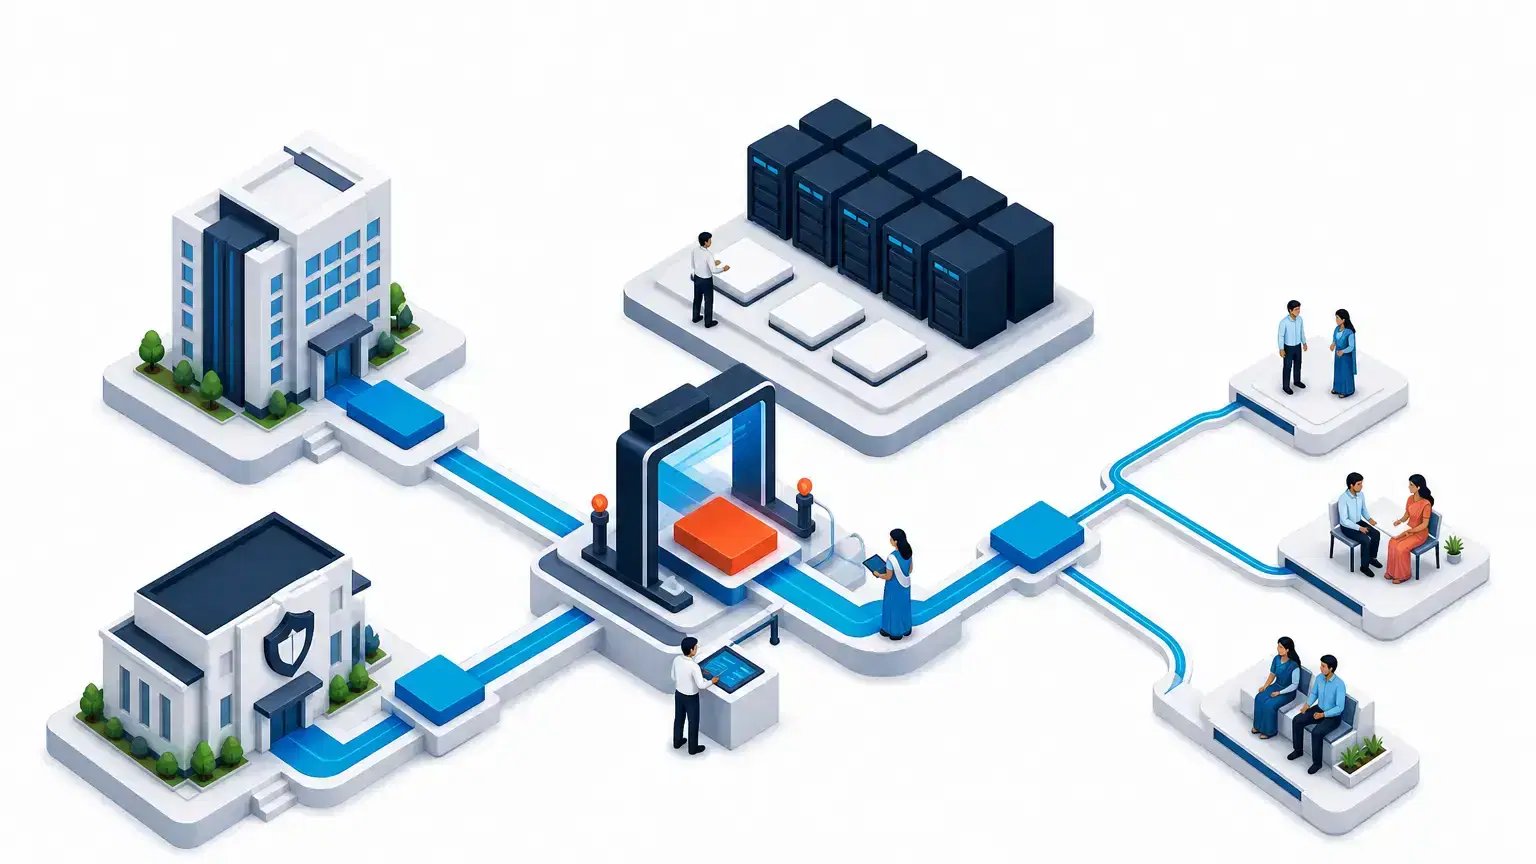
API-led insurance infrastructure can help a platform connect member data, product configuration, policy status and communications to its existing customer journey.
The customer moments that make festive cover relevant
The best festival insurance for platforms begins with relevance, not reach. An offer should appear where the customer can understand both the occasion and the risk in seconds.
For example:
- A payments app can surface optional protection in a Diwali safety or offers section, rather than interrupting an unrelated peer-to-peer payment.
- An e-commerce marketplace can consider cover alongside a category or campaign only where the product, audience and disclosures fit the insurer’s agreed design.
- A gig or delivery platform can explore event-period protection through a worker app when seasonal work patterns create a clearly defined exposure.
- A travel or mobility platform can connect short-duration cover to a documented journey or seasonal travel flow where the product is relevant.
The test is straightforward: Would a reasonable customer understand why this protection is being offered at this moment? If the answer is no, the campaign may create confusion, poor-quality enrolment and avoidable support demand.
Do not turn urgency into pressure. “Limited-period cover” should communicate the policy period, not obscure key conditions. The product summary should distinguish an insured event from an incident outside cover and should not imply that every medical expense or incident will be paid. Insurance remains subject to policy terms, conditions, limits and exclusions.
Designing eligibility, coverage terms and exclusions in plain language
Short term accident insurance India programmes need clear language because customers have less time to compare terms. In the reported PhonePe example, Mint described the cover as protection for firecracker-induced mishaps during the Diwali season. The same discipline applies when a platform launches a different product. Mint’s report
Use a concise customer-facing summary before payment that answers:
- Who can buy and who is covered? State age criteria, geography, relationship rules for family members and other eligibility conditions.
- What does the policy pay for? Separate reimbursement benefits from fixed-benefit payouts. A reimbursement benefit pays eligible expenses subject to the policy; a fixed benefit pays the stated amount when the insured event meets the policy conditions.
- When does cover begin and end? Use exact dates and times where applicable, alongside the duration.
- What is excluded or limited? Set out material exclusions, sub-limits, deductibles, waiting periods and documentation requirements in plain language, then link to the full wording.
- Who is the insurer and who supports the customer? Make the insurer, authorised distribution or servicing arrangement and customer-support route clear.
The IRDAI policyholder-protection regulations require prospectus information to explain features, benefits, exclusions, risks and terms in clear and simple terms. They also prohibit advertisements that mislead or misrepresent facts or features, obscure policy terms, or insufficiently disclose important exclusions, limitations and conditions. A platform should therefore keep campaign creative, app cards, FAQs and support scripts consistent with insurer-approved product and policy materials.
Claims journeys: what the platform must make easy after an incident
The real test of embedded accident cover comes when a customer needs it. A platform should not describe a claims route as seamless unless it has mapped each hand-off, from incident reporting to document collection, insurer or TPA review, query resolution and decision communication.
Build the claim journey around the customer’s immediate questions:
- What should I do now? Provide emergency guidance appropriate to the product, followed by a clearly labelled “start a claim” or “inform us” route. An app flow is not a substitute for urgent medical care.
- Is this event potentially covered? Offer a plain-language initial check, while making clear that coverage is assessed under the policy terms.
- What information is needed? Give a tailored checklist, such as policy details, treatment records, invoices, discharge summary, incident information or other documents specified by the policy.
- Where is my claim now? Show meaningful stages such as intimation received, documents submitted, query raised, under review and decision communicated.
- Who can help? Provide accessible escalation channels and clear contact ownership across the platform, insurer and TPA where one is involved.
The IRDAI policyholder-protection regulations require claim documentation and procedures to be listed in the policy document, and require insurers and applicable distribution channels to provide claim-registration support, stage-wise information and fair treatment. As a practical design principle, the platform can simplify claim intimation, document upload, status visibility and support escalation, while the insurer or the party designated in the programme’s claims operating model assesses the claim and communicates the outcome under the policy. A connected claims experience can give partners a structured interface for those hand-offs without presenting the platform as the decision-maker.
How to measure adoption, service quality and claims outcomes
A festival-linked programme can produce attractive campaign numbers while still failing customers who did not understand the cover or could not navigate the claim process. Use a balanced scorecard.
Adoption and informed choice
- Eligible users reached and offer views
- Completed purchases or enrolments
- Policy-issuance success rate
- Policy-document delivery and retrieval rate
- Pre-purchase FAQ views and support contacts
- Early cancellations or refund requests, where applicable
Operations and service quality
- Time from payment or enrolment to policy issuance
- Failed identity, member-data or payment hand-offs
- Customer-contact rate by journey stage
- First-response and resolution time for support tickets
- Consistency of insurer, policy and benefit information displayed in the app
Claims outcomes
- Claim-intimation completion rate
- Document-submission completion and repeat-query rate
- Time spent at each claims stage
- Status-update delivery rate
- Escalation themes and customer feedback after closure
These measures help product, insurance and operations teams identify the gap between a high-converting offer and a reliable programme. They also create a practical feedback loop: unclear exclusions may appear in claim queries, incomplete policy data may cause issuance failures and weak notifications may create avoidable support contacts.
FAQs: Can platforms offer festival-linked insurance in India?
Can a payment, commerce or consumer platform offer festival-linked insurance in India?
A platform can make a festival-linked product available only when it operates in an IRDAI-authorised distribution or servicing role, or through an arrangement in which the relevant insurance sale and service activities are carried out by an appropriately authorised insurer or intermediary. The IRDAI policyholder-protection regulations define distribution channels to include insurance agents, intermediaries and persons or entities authorised by IRDAI to take part in the sale and service of insurance policies. Customer communications should identify the insurer and should not imply that the platform is itself offering insurance as the insurer.
What should a platform show before a customer buys an embedded accident cover?
Show who is eligible, who is insured, covered events and benefits, the cover start and end dates, key exclusions and limits, required claim documents, the insurer’s identity and the full policy wording. This is especially important for diwali firecracker insurance or any other short-duration product, where customers may decide quickly. The IRDAI policyholder-protection regulations require prospectus information to explain product features, benefits, exclusions, risks and terms in clear and simple terms, and require policy terms and conditions to be simple and clear.
What should be measured in a festive protection launch?
Measure policy-issuance reliability, document delivery, informed conversion, claims-intimation completion, query rates, turnaround time, status communication and customer-support themes, not just campaign clicks or sales.
Who should communicate a claim decision to the customer?
The programme should identify the insurer and any designated claims-service party, explain each party’s customer-support role and state how decisions will be communicated. A platform should make it easier to notify a claim, submit documents, track progress and access help, without suggesting that a claim will be approved or settled. The IRDAI policyholder-protection regulations provide the governing framework for policyholder servicing, claims settlement and grievance redressal.
Talk to BharatSure about a festive protection use case to map product, data, policy-servicing and claims requirements before launch.
Book a demo to explore a white-label, event-led protection journey for your platform, from product configuration to claims servicing.
Frequently asked questions
Can platforms offer festival-linked insurance in India?
A platform can make a festival-linked product available only when it operates in an IRDAI-authorised distribution or servicing role, or through an arrangement in which the relevant insurance sale and service activities are carried out by an appropriately authorised insurer or intermediary. The IRDAI policyholder-protection regulations define distribution channels to include insurance agents, intermediaries and persons or entities authorised by IRDAI to take part in the sale and service of insurance policies. Customer communications should identify the insurer and should not suggest that the platform itself is the insurer.
What should a platform show before a customer buys festive accident cover?
Show eligibility, insured persons, covered events and benefits, cover start and end dates, exclusions, limits, claim-contact details, required documents and the policy wording. The IRDAI policyholder-protection regulations require prospectus information to present product features, benefits, exclusions, risks and terms in clear and simple terms, and require policy terms and conditions to be simple and clear.
Which metrics matter for an embedded festive insurance programme?
Track eligible users reached, informed conversion, policy-issuance success, document-delivery success, claim-intimation completion, document-query rate, turnaround time, status-update delivery and customer-support escalation themes.
Sources
- Mint’s report — livemint.com
- IRDAI (Insurance Products) Regulations, 2024 — financialservices.gov.in
- IRDAI policyholder-protection regulations — financialservices.gov.in
- IRDAI Master Circular on Operations and Allied Matters of Insurers, dated 19 June 2024 — actuariesindia.org